Understanding Health Insurance Terminology
By Saint Francis Health System Staff
Health insurance can be confusing. Understanding a few common terms can help you compare plans, estimate what you may pay, and make better use of your coverage. Health insurance may help pay for services such as doctor visits, preventive care, hospital care, and prescription drugs, depending on the plan.
Important: Every plan is different. Review your plan's Summary of Benefits, Coverage, and Provider directory for details.
Premium
The amount you pay to keep your health insurance active, usually each month. If you have coverage through an employer, the employer may pay part of the premium. Some people who buy coverage through the Health Insurance Marketplace may qualify for financial help.
You pay the premium whether or not you receive medical care.
Deductible
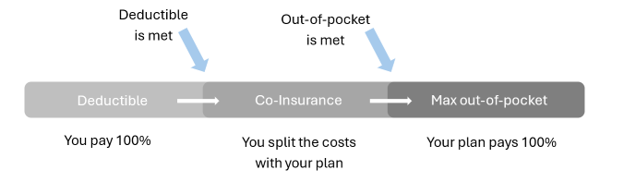
The amount you pay for certain covered services before your plan begins sharing the cost. Some services may be covered before you meet the deductible, and some may not be subject to the deductible. Deductibles usually restart at the beginning of each plan year.
A few things to know about deductibles:
- A plan may have separate deductibles for one person and for a family.
- In-network and out-of-network care may have different deductibles.
- Many plans cover certain in-network preventive services without charging a deductible, copayment, or coinsurance. Coverage rules and exceptions vary.
- A lower deductible often comes with a higher monthly premium, but not always.
Bottom line: check any plan to make sure you understand what deductible you will have to reach before health insurance will start paying.
Copayment (copay)
A fixed amount you pay for a covered service, such as $25 for a primary care visit. Copays can vary by service. Some copays apply before you meet the deductible; others apply afterward. Check your plan for details.
Coinsurance
The percentage of the allowed amount you pay for a covered service, usually after meeting your deductible. For example, if your coinsurance is 20% and the plan’s allowed amount is $100, you pay $20 and the plan pays the remaining $80.
Out-of-pocket max
The most you pay during a plan year for covered, in-network services that count toward the limit. After you reach this amount, the plan generally pays 100% of the allowed amount for covered, in-network services for the rest of the plan year. Deductibles, copays, and coinsurance usually count toward the limit. Premiums, noncovered services, and some out-of-network costs generally do not.
Network
A network is the group of doctors, hospitals, pharmacies, and other providers that have contracted with your health plan. You will usually pay less when you use in-network providers. Before scheduling care, confirm that both the provider and the facility are in network for your specific plan.
Before choosing or using a plan:
- Compare the premium, deductible, copays, coinsurance, and out-of-pocket maximum.
- Check whether your doctors, hospitals, and pharmacies are in network.
- Review which prescriptions and services are covered.
- Read the Summary of Benefits and Coverage. If anything is unclear, contact the health plan.
Relevant Blogs to Read
What Everyone Should Know About Suicide Prevention: Myths, Warning Signs, and How to Help
View Story